Totaled Car Insurance Payout: Valuation, Deductibles and Settlement
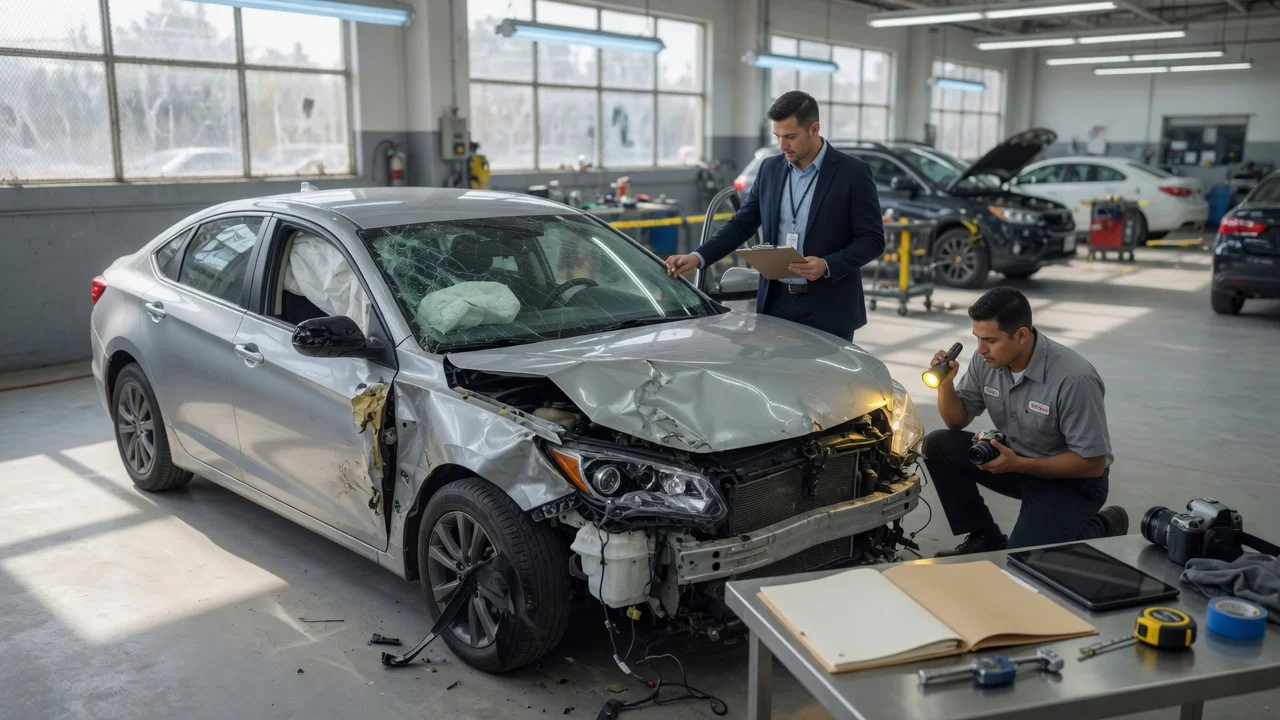
What a totaled car payout is
A totaled car insurance payout is the amount an insurer pays after declaring a vehicle a total loss. The starting point is usually the actual cash value of the vehicle immediately before the loss, not the price paid at purchase, the loan balance or the replacement cost of a similar new car. The payout can be reduced by the policy deductible, and for a financed vehicle the lender may receive part or all of the settlement before the owner is paid.
How the vehicle value is established
Insurers generally begin with the vehicle's actual cash value, which accounts for age, mileage, condition, equipment and local used-vehicle prices. The valuation may be based on comparable listings or sales data rather than private-party asking prices alone. Because valuation methods and comparable vehicles differ, the same car can produce different offers from different insurers or valuation reports.
Condition matters most when it is documented. A pre-loss inspection, recent service records or photos that show newer tires, a clean interior and no prior damage may support a higher value. Existing collision damage, rust, mechanical problems or high mileage can reduce the figure.
Where the deductible fits
For a covered claim, the deductible is generally subtracted from the loss settlement rather than paid separately to the repairer. On a total-loss claim, that means the owner may receive the vehicle value minus the chosen deductible. State rules and insurer practices vary, so the settlement statement should be reviewed to confirm whether the deductible was applied and whether it can be recovered from another party's insurer when the owner was not at fault.
What can reduce the final amount
Policy deductible; Outstanding loan or lease balance when a lender is listed on the policy; Prior damage or condition issues included in the valuation; Gap insurance that may not be included in the primary settlement; Towing, storage or other covered costs handled separately from the vehicle value
When a loan is involved
If the car is financed or leased, the lender often has an interest in the payout. The insurer may pay the lender first up to the outstanding balance and send any remaining amount to the owner. If the vehicle is worth less than the remaining loan balance, the owner can still owe the difference unless gap coverage applies. A totaled car payout therefore does not automatically clear the loan.
Options if the offer seems low
An owner can ask for the valuation report and confirm that the listed trim, options, mileage and condition match the actual vehicle. Missing features or an incorrect trim can lower the figure. If the report is wrong, the owner can provide corrected documentation or comparable vehicles. The policy typically identifies how disputes are handled, which may include negotiation or an appraisal process.
What evidence is needed before accepting
Valuation report showing comparable vehicles and condition adjustments; Settlement statement separating vehicle value, deductible, taxes or fees and lender payment; Loan payoff amount from the lender when applicable; Written confirmation of who receives each portion of the payout
The exact timing and format of these documents depend on the insurer and jurisdiction. State rules may also govern sales-tax treatment, title transfer procedures and whether the owner may retain the salvage. A specific dollar figure cannot be stated without the valuation inputs for a particular vehicle and policy.