Totaled Car Insurance Payout: Valuation and Settlement Deductions
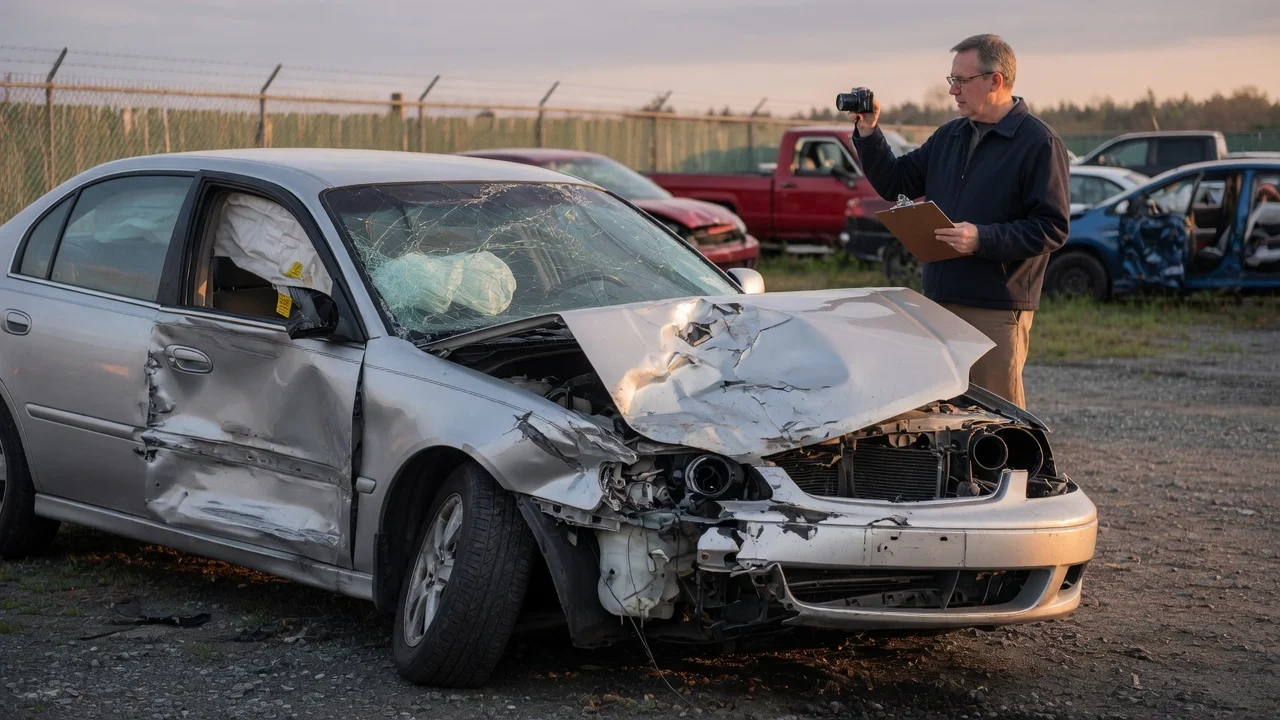
What you are paid when a car is totaled
A totaled-car insurance payout is the settlement for a vehicle the insurer has declared a total loss. In ordinary auto policies, that amount is the car’s actual cash value immediately before the loss, minus the deductible and other settlement deductions. Actual cash value, often shortened to ACV, is a market estimate of what a comparable vehicle would have sold for in your area, after age, mileage, condition, equipment and local demand are taken into account. It is not the original purchase price, the cost of a new replacement, the amount still owed on a loan, or a repair estimate.
That answer holds for standard collision and comprehensive coverage written on an actual-cash-value basis, which is the usual personal-auto form in the United States. It changes when a different party pays, when the policy uses a stated or agreed value, when you keep the wreck, when a lender has a lien, and when state law requires tax or fee items in the settlement. Those qualifications are the difference between the headline ACV figure and the check that clears.
When an insurer calls the vehicle a total loss
A total loss is an administrative decision that repairing the car is not the economical way to settle the claim. Insurers compare expected repair cost with the vehicle’s ACV and, in many markets, also consider what the damaged car would bring as salvage. Some states set a statutory threshold, expressed as a percentage of ACV, at or above which the vehicle must be totaled. Other states leave the decision to the insurer’s total-loss formula, typically treating the car as totaled when repair cost plus salvage value meets or exceeds ACV. The exact percentage, formula and whether airbag, structural or flood damage triggers an automatic total are jurisdiction- and policy-dependent; the claim file and your state’s insurance rules control, not a single national cutoff.
Once the car is totaled, the claim stops being a repair job and becomes a valuation job. The insurer owes the value of the vehicle as it sat before the accident or other covered event, then applies the deductions in the policy and in applicable law.
How actual cash value is built
Valuation starts with comparable vehicles: same generation and body style, similar mileage, similar options, and recent local asking or sold prices. Adjusters and valuation vendors then add or subtract for documented differences. A clean title, recent major service, desirable packages and verifiable low mileage support a higher figure. High mileage, neglected maintenance, worn tires, interior damage, aftermarket modifications that do not hold retail value, and unrepaired prior damage support a lower figure. Guidebook averages are a starting point, not a substitute for local comparables.
Trim, powertrain and model year matter because they define the comparable set. A hybrid or performance variant is not valued as if it were the base gasoline sedan of the same nameplate. Options that buyers still pay for in the used market, such as a towing package or a factory navigation system on a generation that offered it, can move ACV. Owner-installed accessories often do not, unless the policy endorses them or the local market clearly pays more for that equipment.
You are entitled to see the valuation worksheet: the comparables used, the adjustments applied, and any condition or prior-damage deductions. If the comps are the wrong generation, the wrong drivetrain, from a distant market, or ignore recent sales of equivalent cars, that is a valuation dispute, not a repair dispute. Supported evidence includes window stickers, build sheets, service records, photos from before the loss, and listings or sale records for truly similar vehicles. Unsupported asking prices and emotional replacement cost do not reset ACV.
Deductions that reduce the settlement
The ACV offer is the starting number. The amount paid to you, or to you and the lienholder, is ACV after settlement deductions. The common deductions are as follows.
Policy deductible, when you claim under your own collision or comprehensive coverage. The deductible is the portion of the loss you agreed to retain. It is subtracted from ACV, not from a repair estimate, on a total-loss claim. Salvage value, if you retain the vehicle. Keeping the wreck means the insurer pays ACV minus what the salvage is worth, and you typically receive a salvage title subject to state branding rules. If you surrender the vehicle, salvage belongs to the insurer and is not deducted from your check. Unrepaired prior damage and missing equipment. Damage that existed before this loss, or factory equipment that is gone, is not part of pre-loss ACV. Outstanding premium or other policy balances the contract allows the insurer to offset. The lender’s interest. If a bank or finance company is listed as loss payee, the insurer pays the lienholder first up to the unpaid balance, and any remainder of the adjusted ACV goes to you.
Betterment, the reduction for replacing old parts with new ones, is a repair-settlement concept. On a total loss it should not appear as a separate line if the car is being valued as a used vehicle; wear is already inside ACV. If a betterment or like-kind-and-quality deduction shows up on a total-loss worksheet, ask that it be explained against the ACV method in the policy.
Sales tax, title fees and registration are treated differently by state. Some jurisdictions require the insurer to include applicable sales tax and certain replacement fees in a total-loss settlement so the owner can put a comparable vehicle on the road. Others limit the obligation to ACV of the damaged car. Whether those items are in your check is a legal and policy question for the state of the loss and the contract, not a universal add-on.
Qualifications that change who pays and how much
If you are claiming on your own collision coverage after a crash, or comprehensive coverage after theft, fire, flood or similar named perils, your policy’s ACV and deductible rules apply. If an at-fault driver’s liability insurer is paying, the measure is still typically the fair market value of your car, but your collision deductible is not the starting subtraction, and that insurer’s valuation methods and state liability rules govern. You can often claim collision first for speed, then recover the deductible through subrogation if the other party is at fault; that sequence is a claims-handling choice, not a change in the underlying ACV.
Stated-value and agreed-value endorsements, more common on collector, classic and some specialty policies, replace market ACV with a scheduled amount. Agreed value, where the contract sets the payout in advance, is a different bargain from ACV. A stated-value policy may still allow the insurer to pay the lesser of the stated amount and ACV unless the form says otherwise. Read the declarations and the valuation clause; the label on the binder is not enough.
A loan or lease larger than ACV is a credit problem, not an insurance valuation error. Collision and comprehensive pay ACV, not the contract payoff. Guaranteed asset protection, commonly called gap coverage, is a separate product that can pay the difference between the insurance settlement and the remaining balance, subject to its own exclusions, such as overdue payments, excess mileage on a lease, or prior damage. Without gap coverage, the owner remains responsible for any shortfall after the insurer pays the lienholder.
Use of the vehicle can also change the outcome. A personal-auto policy may restrict or exclude coverage when the car was used as a livery, delivery or other business conveyance outside the policy’s permissions. Commercial auto, garage and motor-truck cargo forms use different valuation and deductible structures. The payout described here is the personal-auto total-loss pattern unless the declarations show another form.
What the settlement check does not buy
ACV does not fund a new car of the same nameplate, optional new-car replacement coverage aside. It does not automatically include a rental car for as long as you shop; transportation expense is a separate limit and number of days, if purchased. It does not restore aftermarket stereo, wheels or wraps unless those items are scheduled or the valuation documents a market increment. Personal property inside the car is usually a homeowners or renters question, not an auto total-loss line, except for equipment permanently installed and covered by the auto form.
There is no single public database that is the legal ACV of your car. Different insurers and vendors can produce different numbers from different comparable sets. Material gaps in any given claim include the unpublished internals of the vendor model, the precise state threshold that applied, and unpublished insurer guidelines for condition ratings. Those gaps are closed with the worksheet, the policy, and, if needed, a state appraisal clause or insurance-department complaint process, not with a national average.
Next actions on a total-loss offer
Ask for the total-loss letter, the ACV report with comparables, the deductible, any salvage or prior-damage deduction, and the statement of who will be named on the check. Confirm whether sales tax and replacement fees are included under your state’s rule. If a lender is involved, get the payoff quote dated through the expected funding day so interest does not silently widen a gap. If you want to keep the car, get the salvage deduction in writing and check title-brand and inspection rules before you agree.
If the number is wrong, dispute the comparable set and the condition adjustments with documents, then use the policy’s appraisal clause if the form provides one and the disagreement is over value rather than coverage. Coverage disputes, such as whether the loss is excluded, follow a different path than valuation disputes. Until you accept the settlement, avoid signing a release that waives the right to correct a documented error in ACV or in a deduction that the policy or state law does not allow.