Liability versus collision car insurance
The short answer
Liability insurance and collision insurance protect different people. Liability coverage pays for injuries and property damage you cause to others when you are at fault in a crash. Collision coverage pays to repair or replace your own vehicle after it hits another vehicle or an object, regardless of who is at fault, minus your deductible. They are not alternatives that do the same job, so the real question is usually whether you need collision in addition to liability, not which one to pick instead of the other.
One qualification matters for most US drivers. Nearly every state requires drivers to carry at least a minimum amount of liability coverage, or to show some other form of financial responsibility. Collision is generally optional under state law, but a lender or leasing company will usually require it if you finance or lease the car. Requirements vary by state and by contract, so check your state's rules and your loan or lease agreement before changing coverage.
What liability insurance covers
Liability coverage is typically split into two parts. Bodily injury liability pays for other people's medical costs, lost income and related claims when you injure them in an at-fault accident, and it can help pay legal defense costs if you are sued. Property damage liability pays to repair or replace property you damage, such as another driver's car, a fence or a building.
Liability limits are often written as three numbers separated by slashes. In order, they usually represent the maximum paid for bodily injury per person, bodily injury per accident, and property damage per accident. If a claim exceeds your limits, you may be personally responsible for the remainder.
Liability coverage does not pay to repair your own car, and it does not pay for your own injuries. Those needs are handled by other coverages.
What collision insurance covers
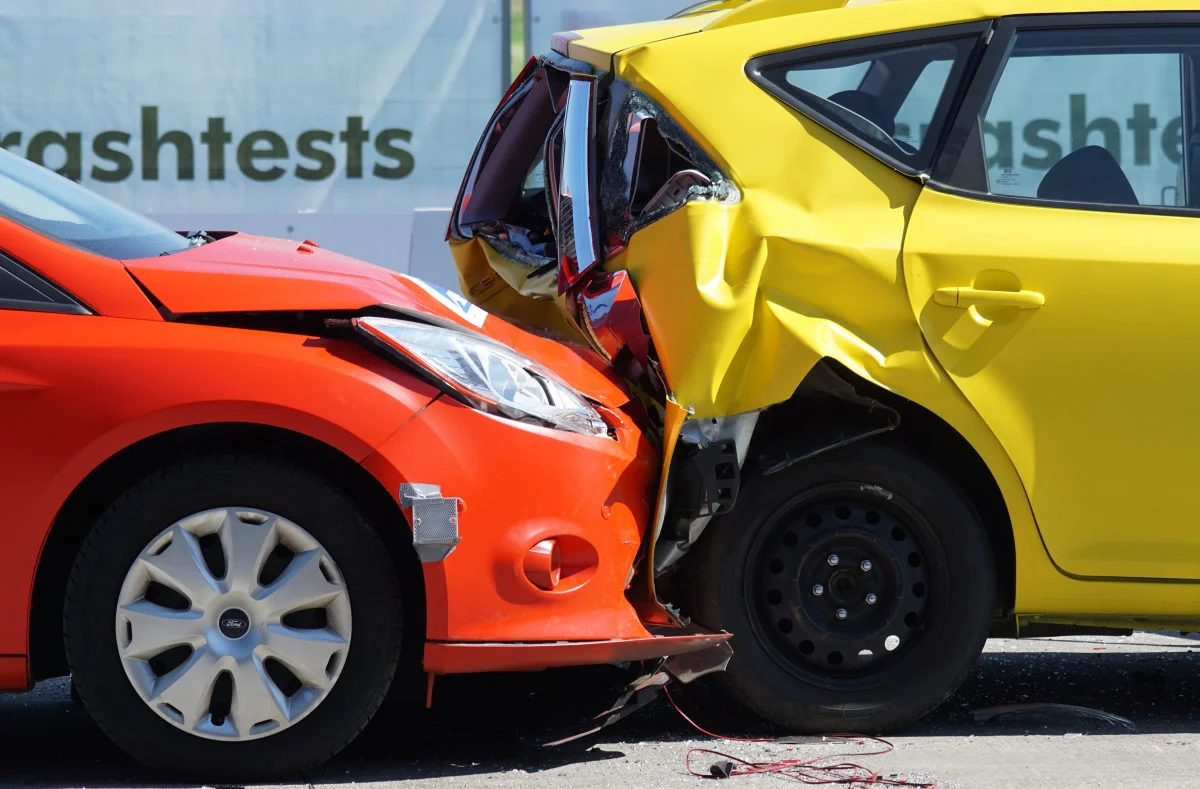
Collision coverage pays for damage to your own vehicle when it collides with another vehicle or an object, such as a pole, guardrail or wall, and it typically applies to single-car accidents and rollovers. It pays regardless of fault, although if another driver caused the crash, your insurer may seek reimbursement from that driver's insurer and you may be able to recover your deductible.
Two terms shape what collision actually pays. The deductible is the amount you pay out of pocket on each claim before coverage applies; choosing a higher deductible generally lowers the premium. Actual cash value is the market value of your car at the time of the loss, accounting for depreciation; if repairs would cost more than the car is worth, the insurer may declare it a total loss and pay its actual cash value minus the deductible, not the cost of a new car.
Collision does not cover theft, vandalism, fire, flooding, hail, falling objects or animal strikes. Those losses are usually covered by comprehensive insurance, a separate optional coverage often bought alongside collision.
Side-by-side comparison
Criterion | Liability | Collision; Whose losses it pays | Other people's injuries and property | Your own vehicle; Depends on fault | Applies when you are legally responsible | Applies regardless of fault; Required by state law | Required in nearly all states | Generally optional; Required by lenders or lessors | Not the lender's main concern | Usually required on financed or leased cars; Deductible | Typically none on liability claims | Yes, chosen by you; Maximum payout | Your selected policy limits | Your car's actual cash value, minus the deductible; Main risk it addresses | Being held financially responsible for harm to others | Paying out of pocket to repair or replace your car
Which differences matter for your situation
Because liability is usually mandatory, the practical decisions are how much liability to carry and whether collision is worth adding. The following situations show how the tradeoffs typically play out.
Financed or leased car: Collision, and usually comprehensive, is typically a condition of the contract. Dropping it can breach the agreement, and the lender may add costly coverage on your behalf. Keep it until the loan is paid off or the lease ends. Newer or higher-value car you own outright: Collision is often worthwhile if you could not comfortably pay to repair or replace the car yourself after an accident. Older or low-value car you own outright: Collision may cost more over time than it could pay out. Compare the annual premium plus your deductible against the car's current market value. If the potential payout is small relative to those costs, and you could absorb the loss of the car, liability-only coverage may be reasonable. Tight budget with savings to cover a repair: Raising the collision deductible is an alternative to dropping collision entirely, since it usually lowers the premium while keeping protection against a major loss. Drivers with significant assets or income: Consider liability limits above your state's minimum. Minimum limits can be exhausted by a single serious accident, leaving you exposed to a lawsuit for the difference.
In general, a policy with only liability coverage protects other people from you and protects you from being held liable, but leaves your own car unprotected. Adding collision protects your investment in the car. The right combination depends on whether the car is financed, what it is worth and how much financial loss you could handle on your own.
Related coverages to know about
Neither liability nor collision covers everything. Comprehensive covers non-collision damage to your car. Uninsured and underinsured motorist coverage helps if an at-fault driver has no insurance or too little. Medical payments coverage or personal injury protection helps with your own and your passengers' medical costs, and some states require it. The informal phrase full coverage usually means liability plus collision and comprehensive, but it is not a standard policy type, so confirm exactly which coverages a quote includes.
What this article cannot tell you
No verified figures were available for premiums, state minimum liability limits, typical deductibles or claim payouts, so none are given here. Costs depend heavily on your state, vehicle, driving record and insurer, and state minimum requirements change over time. For accurate numbers, review your state insurance department's current requirements, your lender or lease terms and quotes from several insurers using the same limits and deductibles so the comparison is fair.
Next steps
Confirm your state's current minimum liability requirements. Check your loan or lease agreement for required coverages and maximum allowed deductibles. Look up your car's current market value to judge whether collision is still worth its cost. Request quotes with identical liability limits and deductibles from multiple insurers. Decide whether liability limits above the state minimum make sense for your assets and income.