Mitsubishi Xpander car loan in the Philippines
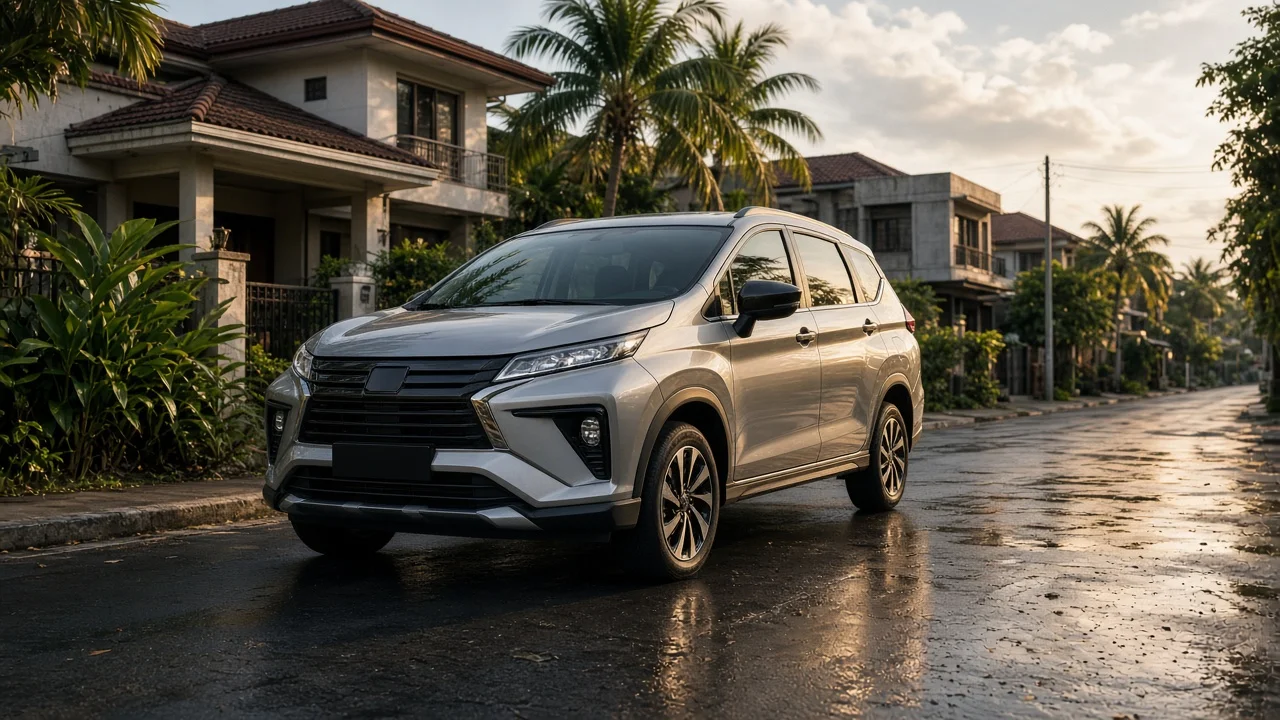
Choosing a Mitsubishi Xpander in the Philippines often begins with understanding how a car loan affects the total purchase. A loan turns a showroom price into a long-term financial commitment, so the useful comparison is not just the monthly payment but the combined cost of interest, insurance and upkeep. Buyers researching this compact seven-seater should connect financing terms to the vehicle's condition, mileage, trim level, inspection findings and ownership costs. That context helps separate a genuinely affordable unit from one that only appears cheaper at first glance.
The direct answer
A Mitsubishi Xpander car loan in the Philippines is workable when the applicant has stable income and a documented financial history, because lenders focus on repayment capacity rather than the vehicle alone. The practical answer is to compare the down payment, loan tenor and monthly amortization against the total amount financed. A shorter term usually reduces total interest but raises each installment, while a longer term lowers the monthly burden without changing other fixed ownership costs. Without confirmed regional rates, buyers should treat every advertised quote as conditional until the bank or dealership verifies the applicant.
The immediate next step is to establish the all-in price of the specific unit, including dealer charges and insurance, then request a computation sheet from at least two lenders. Because the data supplied does not confirm exact figures, the safest interpretation is that published monthly estimates may not reflect a particular buyer's approved rate. Choosing a sensible loan therefore means comparing the effective interest cost across identical loan amounts and terms. It also means checking that the Xpander's trim, mileage and condition support the financed price, since the vehicle serves as collateral.